
New York Form IT-2104-SNY lets eligible START-UP NY employees stop state and local income tax withholding. The key test is working at least six months at your employer’s approved location.
That six-month test and the rules below come from the Tax Department’s 2026 form, its START-UP NY pages, and the state’s FAQs.
One limit: the program closed to new applicants January 1, 2026, so only already-approved employers have eligible staff.
Last reviewed: October 9, 2026
What Is New York Form IT-2104-SNY?
Form IT-2104-SNY is a certificate you give your employer, not the Tax Department. It names New York State, New York City, and Yonkers income tax, and your employer keeps withholding until it arrives. You must hand in a new one every year.
What the Form Does and Who Uses It
The START-UP NY program gives approved businesses a tax break, and some of their workers get one too. These businesses operate in zones called Tax-Free NY areas. If you hold a qualifying new job there, all or part of your wages can be left out of your New York income. That is the START-UP NY wage exclusion. Form IT-2104-SNY 2026 only changes withholding, the tax taken out as you go. Get it from the New York State Department of Taxation and Finance’s official IT-2104-SNY PDF. The IT-2104-SNY instructions are printed on the form.
What Taxes Can the Exemption Affect?
The form stops state and local income tax withholding only. Federal taxes and payroll taxes still come out of every check, along with other New York paycheck deductions.
| Withholding the form stops | Still taken from every check |
|---|---|
| New York State personal income tax | Federal income tax |
| New York City resident income tax | Social Security |
| Yonkers resident income tax surcharge | Medicare |
| Yonkers nonresident earnings tax |
Federal adjusted gross income (FAGI) still includes your START-UP NY wages. New York subtracts the excluded amount to get New York adjusted gross income (NYAGI). Withholding is only a prepayment. What you owe is settled on your return, based on the 2026 New York tax brackets.
IT-2104-SNY vs. IT-2104 vs. IT-2104-E
Form IT-2104, the Employee’s Withholding Allowance Certificate, sets your withholding. Form IT-2104-E stops it for two groups: people under 18, over 65, or full-time students under 25 who owed no New York tax last year and expect none this year, and qualifying military spouses under the Servicemembers Civil Relief Act (SCRA). IT-2104-SNY stops it because your wages qualify under START-UP NY. The first is the standard form. The other two are exemptions.
Key Differences Between the Three Forms
| Form | What it does | Who it is for |
|---|---|---|
| IT-2104 | Sets your withholding using allowances and filing status | Employees who are not claiming an exemption |
| IT-2104-E | Stops withholding for two groups: no-tax filers who meet an age or student test, and qualifying military spouses | People under 18, over 65, or full-time students under 25 with no New York tax last year or expected this year, and military spouses covered by the SCRA |
| IT-2104-SNY | Stops withholding on START-UP NY wages | Eligible employees of approved START-UP NY businesses |
IT-2104-SNY depends on your job and where you work, not your income or allowances. It is not a general exemption, so a worker at an ordinary New York employer cannot use it. IT-2104-E depends on age or student status plus owing no tax (or on military spouse status under the SCRA), and it expires April 30, 2027, so you refile yearly. Form IT-225 is not a paycheck form. It goes with your tax return. The regular IT-2104 was revised for 2026, and the Tax Department updated its State and Yonkers withholding tables effective January 1, 2026.
The federal Form W-4 does not replace it, as our New York W-4 vs IT-2104 guide explains. Form IT-2104.1 is a separate certificate of nonresidence and allocation of withholding tax. More forms are covered in our New York tax forms and withholding guides.
Who Qualifies for IT-2104-SNY in 2026?
You qualify if you work for a certified START-UP NY business, hold a net new job there, work at its approved location, and work at least six months of the tax year. Miss one and you cannot claim the exemption.
Employee Eligibility Checklist
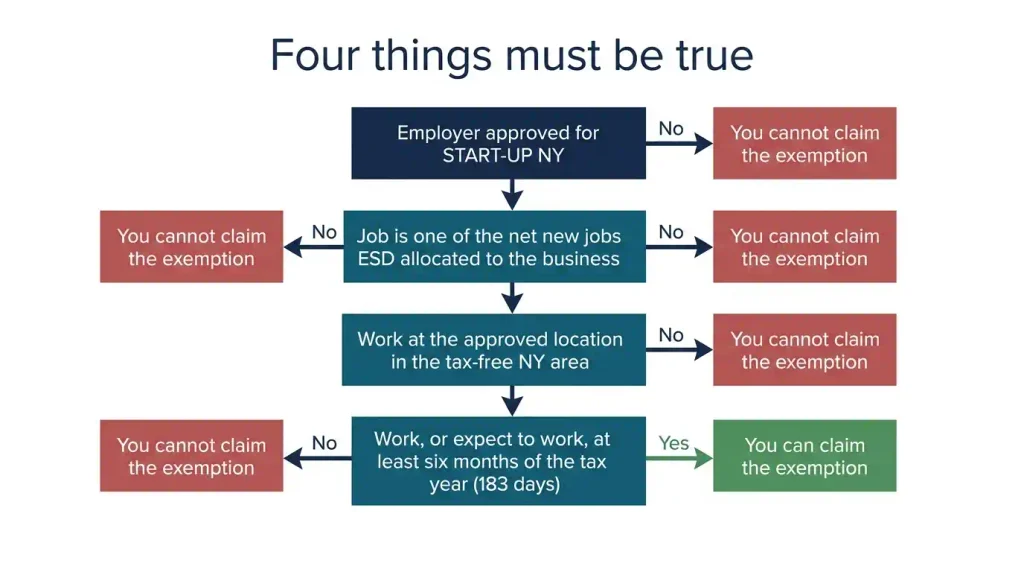
Four things must be true:
- Your employer is approved for START-UP NY.
- Your job is one of the net new jobs Empire State Development (ESD) allocated to the business, and your employer is supposed to notify you if it is.
- You work at the approved location in the tax-free NY area.
- You work, or expect to work, at least six months of the tax year there. The Tax Department counts that as 183 days.
Does Your Work Arrangement Qualify?
The form requires work exclusively at the approved location. Work outside the tax-free area must be minimal and incidental. A regular hybrid or remote schedule does not fit, and neither does splitting your week between two sites. An approved employer is not enough, because the job and location must both qualify. Hours matter too. State law (Economic Development Law §431) defines a net new job as a full-time wage-paying job or equivalent, requiring at least 35 hours a week. The ESD FAQs say the same. A part-time role below that may not qualify, so ask HR how your position was counted.
When Employees May Not Qualify
The Tax Department says new hires generally must start on or before July 1 to reach 183 days that year. Leaving early has the same effect. A transfer to a different job or building can also end eligibility, because the benefit follows the allocated job and approved location. Ask HR to confirm in writing that your job and location qualify. If your employer will not, let regular withholding continue for now.
How to Fill Out Form IT-2104-SNY Step by Step
Get the 2026 form, fill in your section, have your employer fill in theirs, and give it to payroll. The hard part is knowing you qualify before you sign.
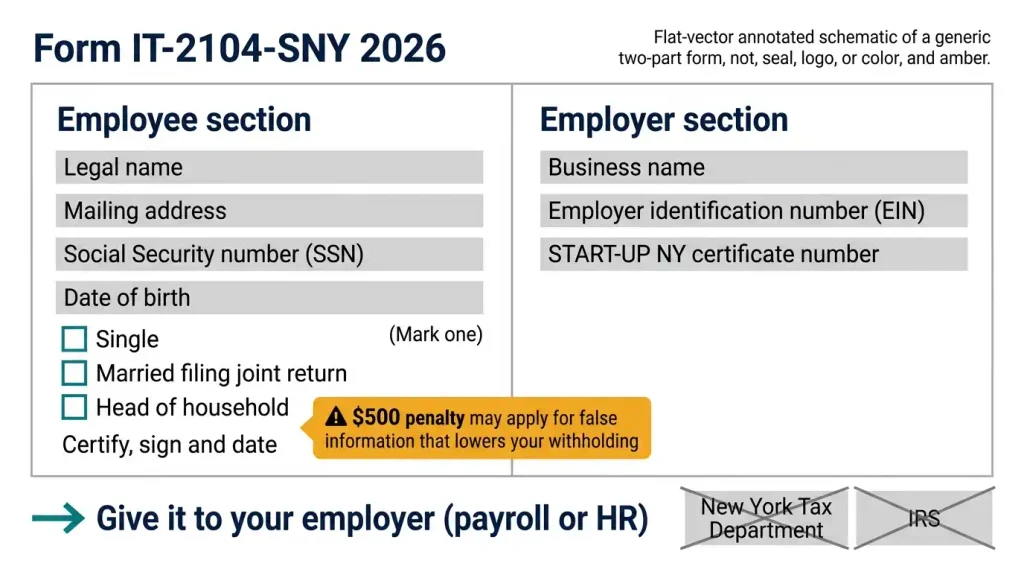
Get the Correct 2026 Form
Download it from the Tax Department’s withholding allowance certificates page, listed as the 2026 Certificate of Exemption from Withholding for START-UP NY Program. Check that the tax year says 2026. First ask HR to confirm the four points in the eligibility checklist above.
Complete the Employee Section
Enter your legal name, mailing address, Social Security number (SSN), and date of birth. Mark one filing status box: Single, Married filing joint return, or Head of household. Then certify that you meet the conditions, and sign and date it. Leave no blanks, and do not certify on a hunch. A $500 penalty may apply for false information that lowers your withholding.
Complete the Employer Section
Your employer enters the business name, its employer identification number (EIN), and its START-UP NY certificate number from its certificate of eligibility. It also certifies that the business takes part in the program. You certify only for yourself. START-UP NY employer reporting is also theirs. They keep your form on file, report wages each quarter on Form NYS-45, Quarterly Combined Withholding, Wage Reporting, and Unemployment Insurance Return, and file an annual summary through New York Tax Department Online Services by January 31. A missed deadline can mean the benefit is denied. Your job is to file your own return. Our New York payroll tax deadlines and employer compliance guides cover related filings.
Where to Submit the Completed Form
Give it to your employer, usually payroll or HR. Do not mail it to the New York Tax Department or the IRS. Keep a copy, since your employer holds the original for inspection. Check your next paystub or two. If state and city tax still come out, ask payroll if they received it. For other causes of a lower check, see why your New York paycheck is lower. Tax withheld meanwhile counts toward your final New York bill on your return.
What Happens After You Submit IT-2104-SNY?
Your employer stops withholding New York State, New York City, and Yonkers income tax, so your take-home rises. You still file a New York return and claim the START-UP NY wage subtraction on Form IT-225.
How the Form Changes Your Paycheck
Eligible employees are not exempt automatically. Your employer keeps withholding until you give them a completed form. Say you earn $5,000 a month before tax. Whatever state and city tax came out of each check, which depends on your pay and where you live, now stays in your account. Your gross pay does not change. But less withholding is not less tax. If you were not eligible, you owe it back. Run your own numbers in our New York paycheck calculator, and see our calculation methodology for how it works. For other salaries, see $80K after taxes in New York or $200K after taxes in New York State.
Do You Still Need to File a New York Tax Return?
Yes, even if START-UP NY wages are your only income. Claim the START-UP NY wage subtraction modification on Form IT-225, New York State Modifications, and submit it with your state return. Your employer should report those wages on Form W-2 under W-2 Box 14 code SNY. The same pay still sits inside W-2 Box 1 wages and W-2 Box 16 state wages. On your federal return, report wages as usual. The benefit covers New York income tax only. If you live outside New York, see how New York taxes nonresidents and the resident vs nonresident income tax rules for the general filing picture.
What Happens if You Have Other Income?
The form covers only your START-UP NY wages. A second job, freelance pay, or interest, dividends, and other investment income can still be taxed by New York, with no withholding. If you have a second job, see how to get your New York withholding right with multiple jobs. You may need estimated payments on Form IT-2105, Estimated Tax Payment Voucher for Individuals, to avoid penalties and interest. If your freelance work might really be a job, see 1099 vs W-2 in New York and what to do if you were misclassified as an independent contractor.
Real-World IT-2104-SNY Examples
Three made-up cases show where the form helps and where it bites. For more worked cases, see our New York paycheck scenarios.
An Eligible Employee Working at an Approved Location
Maya is hired in January as a lab technician at an approved business. HR confirms her job is an allocated net new job. She works on site all year and gives payroll Form IT-2104-SNY in her first week. She enters her legal name, address, Social Security number, and date of birth, marks Single, and signs and dates it. Payroll adds the business name, EIN, and certificate number. State and city withholding stops. Her W-2 later shows her wages in box 14 with code SNY, and she claims the subtraction with Form IT-225 on her New York return.
A Hybrid Employee Who Regularly Works Remotely
Jordan works three days a week at the approved site and two from home. Two days every week is routine, not minimal and incidental. Jordan should not sign until HR explains in writing how the company treats those days. If Jordan claimed the exemption and does not qualify, Jordan owes tax on those wages.
An Employee Hired Late or Leaving Early
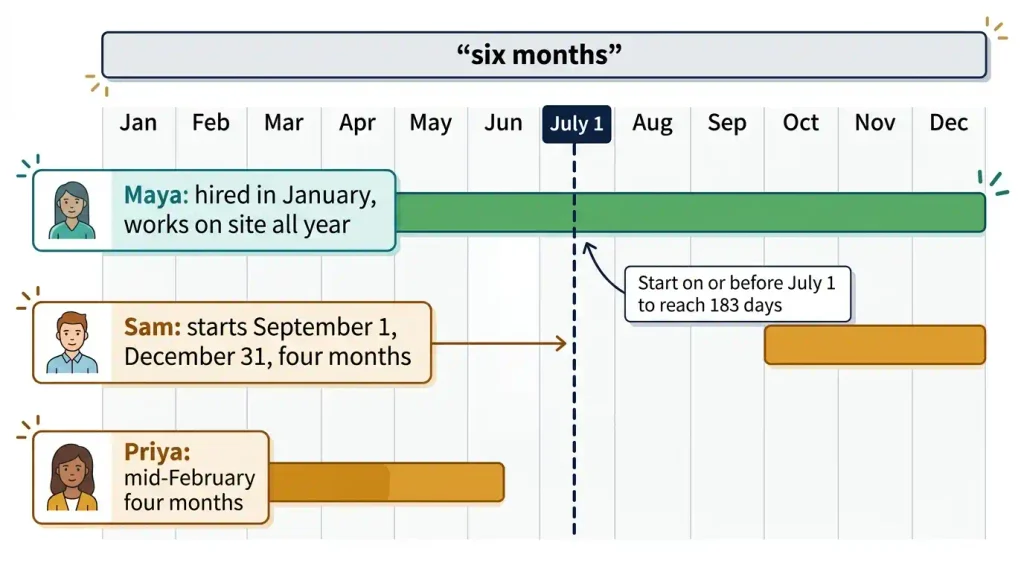
Sam starts September 1 and files the form, assuming it works as it did for coworkers hired in spring. By December 31, Sam has worked four months, short of the six required. Priya starts in mid-February and plans to stay, but leaves in mid-June after four months. Her claim made sense when she signed, but it fails. Both can owe New York tax on wages never withheld, and a penalty may apply.
Special Situations That Can Affect Eligibility
Four situations change eligibility: a late start, an early exit, a change in your employer’s START-UP NY status, and work outside the approved area. The Tax Department’s employee information page explains the main rules.
You Started the Job After July 1
A start after July 1 generally means you cannot reach 183 days, so you generally will not qualify for the wage exclusion that year. Confirm your start date with your employer before claiming anything. You can file a new form next January if you will be eligible then.
You Leave the Job Before Six Months
If you claim the exemption and then do not work six months, you will be liable for income tax on all those wages and may face a penalty. Tell payroll when your plans change, and set money aside. If you take a new job, give that employer a regular Form IT-2104 so tax is withheld again.
Your Employer’s START-UP NY Status Changes
A business can have its participation suspended or terminated, or its ten-year benefit period can end. An employee who would otherwise be eligible may still claim exemption from withholding for the rest of that year. Since no new employers can join, ask HR when your employer’s benefit period ends. Withholding relief is about your paycheck. The final wage exclusion still depends on meeting the eligible employee rules, including six months at the approved location.
You Work Remotely or Outside the Approved Area
The exception is narrow. A one-time training trip or occasional off-site meeting may be minimal and incidental. Working from home every Friday is not. Get your employer’s position on where your work counts as performed in writing, and base your signature on it.
Common IT-2104-SNY Mistakes and Misconceptions
Four ideas cause most trouble: that an approved employer makes you eligible, that the form wipes out all tax, that one form lasts forever, and that a wrong claim is harmless. None is true.
Does an Approved Employer Automatically Make You Eligible?
No. The job must be a net new job the state allocated to the business. A hire into a job outside that allocation does not get the wage exclusion.
Does the Form Eliminate All Taxes on Your Wages?
No. It only stops New York State, New York City, and Yonkers income tax withholding. Federal income tax, Social Security, and Medicare still apply. The exclusion also depends on where the business is in its ten-year benefit period, and workers hired after the business’s first year get fewer than ten years.
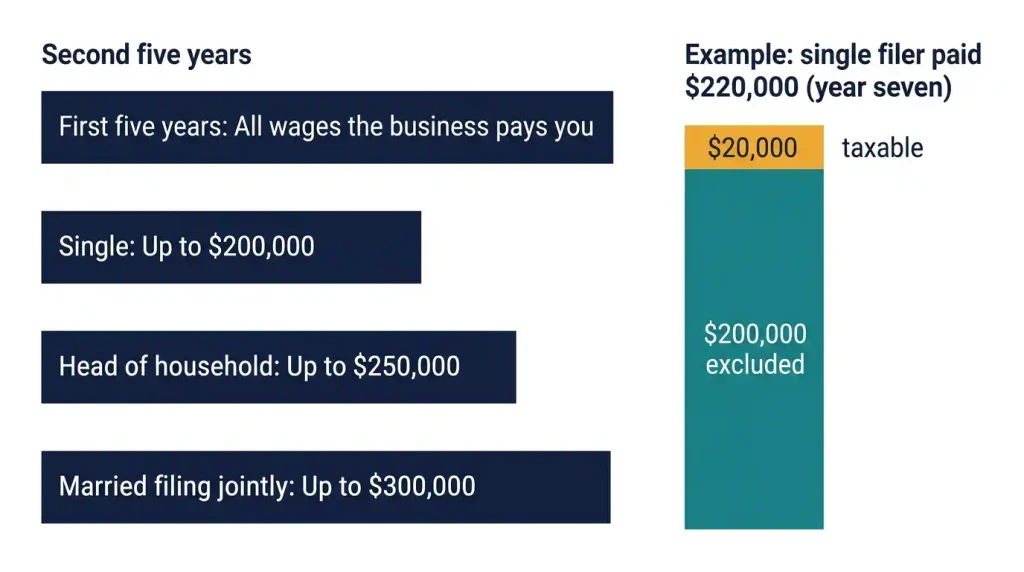
| Benefit period | Wages excluded |
|---|---|
| First five years | All wages the business pays you |
| Second five years, single | Up to $200,000 |
| Second five years, head of household | Up to $250,000 |
| Second five years, married filing jointly | Up to $300,000 |
File a regular IT-2104 so the right amount is withheld from wages above the cap. For example, a business in year seven pays a single filer $220,000. The first $200,000 is excluded and the other $20,000 is taxable. You still claim the subtraction on your return.
Can You Submit the Form Once and Use It Every Year?
No. Submit the form each year to keep the exemption, and confirm each year that you still qualify. Last year’s form leaves you with the wrong paycheck.
What If You Claim the Exemption Incorrectly?
You can owe the tax plus interest and penalties, including a $500 penalty for false information that lowers withholding. Give your employer a regular Form IT-2104 so withholding restarts, and talk to a tax professional if you already underpaid. This guide is general information, so see our disclaimer.
Frequently Asked Questions About Form IT-2104-SNY
The form is optional, goes to your employer, and renews yearly.
Is Form IT-2104-SNY mandatory for every START-UP NY employee?
No. You use it to request exemption when eligible. Without a valid form, your employer must keep withholding New York income tax.
Where can I download the 2026 IT-2104-SNY form?
From the Tax Department’s withholding forms page or the direct PDF. It should show tax year 2026.
Do I send IT-2104-SNY to my employer or the IRS?
To your employer. Not the IRS, and not the New York Tax Department.
Do I need to file a New York tax return if no tax was withheld?
Yes. Claim the wage subtraction with Form IT-225. Final tax is worked out on the return, not through withholding.
Can I qualify if I work from home part of the week?
Probably not on a regular schedule. The rule is exclusive work at the approved location, with only minimal and incidental work elsewhere. Confirm with HR before you sign.
What happens if I do not work for the employer for six months?
You can lose the wage exclusion and owe tax on all those wages, plus interest, and a penalty may apply.
Do I need to submit a new IT-2104-SNY every year?
Yes. Submit a new one yearly and recheck that you qualify.
Can I owe New York tax even after submitting IT-2104-SNY?
Yes. Other taxable income, or ineligibility, can leave a balance due. Estimated payments on Form IT-2105 can help.
Final Checklist Before Submitting IT-2104-SNY
Sign only if you can say yes to four things. Your employer is approved. Your job is an allocated net new job. You work at the approved location. You will work there at least six months of the tax year.
Verify Your Eligibility and Keep Your Records
Get HR to confirm those points in writing. Check that the form is the 2026 version, complete, and signed, with the employer’s section filled in. Hand it to payroll and keep a copy with the written confirmation, and later your W-2 showing code SNY. Plan to file your New York return with Form IT-225. If unsure about any point, hold off. Tax keeps coming out, and if you qualify you can still claim the subtraction on your return. For help, see START-UP NY employee information. Employers can use START-UP NY employer information and Publication NYS-50.
Sources: IT-2104-SNY (2026), IT-2104-E (2026), ESD START-UP NY program, ESD START-UP NY FAQs, Withholding tax rate changes
Meet Yasin Ali, Founder
Yasin built NY Paycheck Calculator in 2020 after getting fed up with calculators that treated New York like every other state. Most tools ignore the extra local tax NYC and Yonkers workers pay on top of state tax — or skip New York’s Paid Family Leave deduction entirely.
He keeps the numbers current, checking in regularly against the latest IRS, NY Department of Taxation and Finance, and Paid Family Leave rates.
All results here are estimates based on official sources. For advice specific to your situation, talk to a tax professional.