
A $80,000 salary in New York nets an estimated $61,387 a year outside NYC or $58,721 inside NYC in 2026, after federal, state, and FICA tax, assuming a single filer taking the standard deduction with no bonus or overtime.
That gap comes from New York’s 2026 rate schedule (Publication NYS-50-T-NYS), which taxes income through nine brackets running from 3.9% to 10.9%.
These are estimates only. Actual take-home varies with bonuses, benefits, and NYC or Yonkers residency.
How Much Is $80K After Taxes in New York in 2026?
Here is the full breakdown by tax category, plus the paycheck-frequency numbers.
Estimated Take-Home Pay on an $80,000 New York Salary
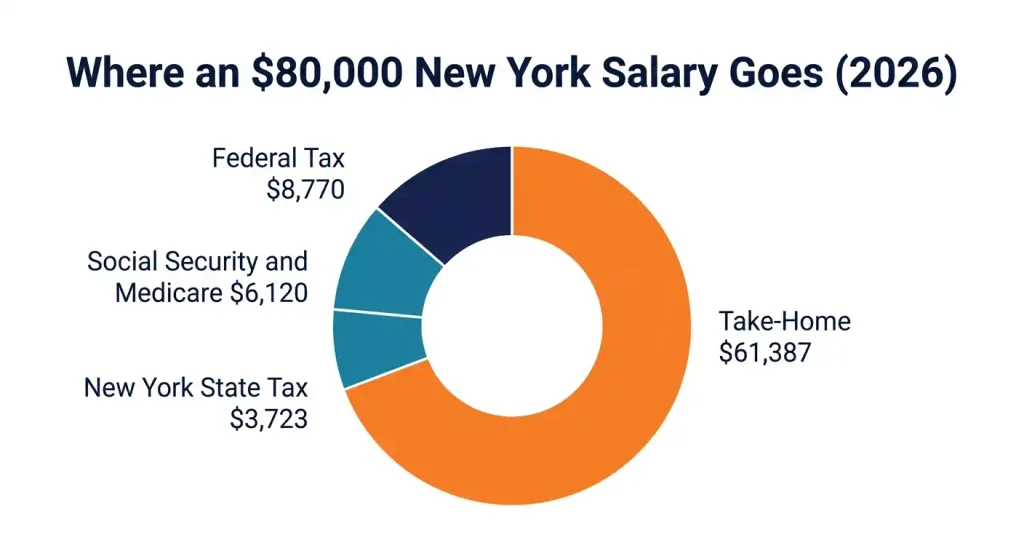
Assuming single, standard deduction, no pre-tax deductions: federal tax $8,770, Social Security and Medicare $6,120, New York State tax $3,723. Outside NYC that leaves about $61,387. Add NYC resident tax and it drops to about $58,721. See the full calculation methodology behind these figures.
$80K Take-Home Pay at a Glance
| Outside NYC | Inside NYC | |
|---|---|---|
| Gross salary | $80,000 | $80,000 |
| Federal tax | $8,770 | $8,770 |
| Social Security + Medicare | $6,120 | $6,120 |
| NY State tax | $3,723 | $3,723 |
| NYC tax | $0 | $2,666 |
| Estimated net pay | $61,387/yr | $58,721/yr |
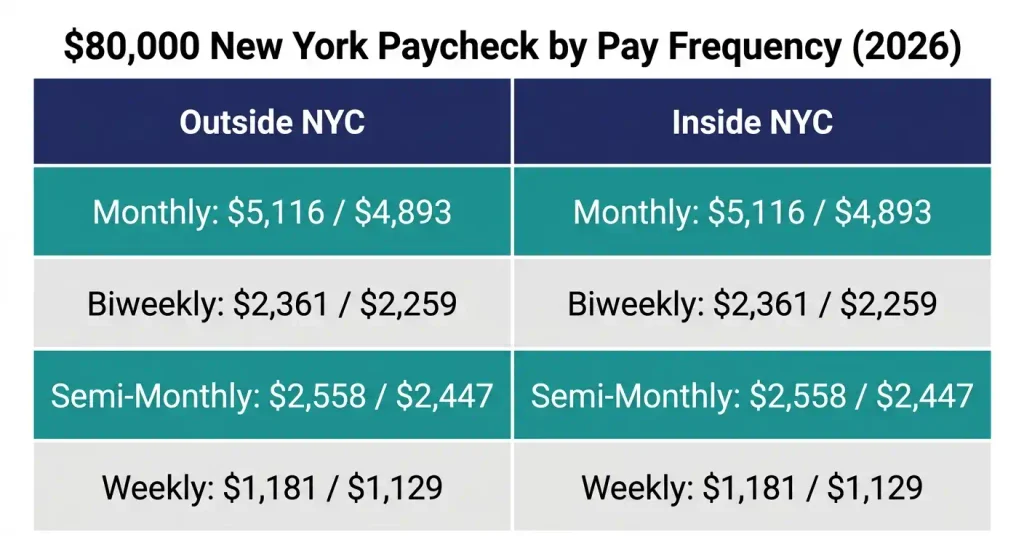
| Monthly | $5,116 | $4,893 |
| Biweekly | $2,361 | $2,259 |
| Weekly | $1,181 | $1,129 |
What Assumptions Does the $80K Estimate Use?
Assumes a single filer with the 2026 standard deduction, $16,100 federal and an $8,000 New York State standard deduction, paid a flat $80,000 with no bonus, no overtime, no pre-tax benefits, living in New York all year. A bonus withholds at a flat 22% federal supplemental rate. New York taxes overtime as regular wages, but under the 2026 OBBBA rule, up to $12,500 of federal overtime pay ($25,000 married filing jointly) can be deducted, phasing out above $150,000 MAGI single or $300,000 MFJ. For a personalized number, plug in your real salary, filing status, city or Yonkers residency, and deductions into a New York paycheck calculator.
$80K After Taxes by New York Location
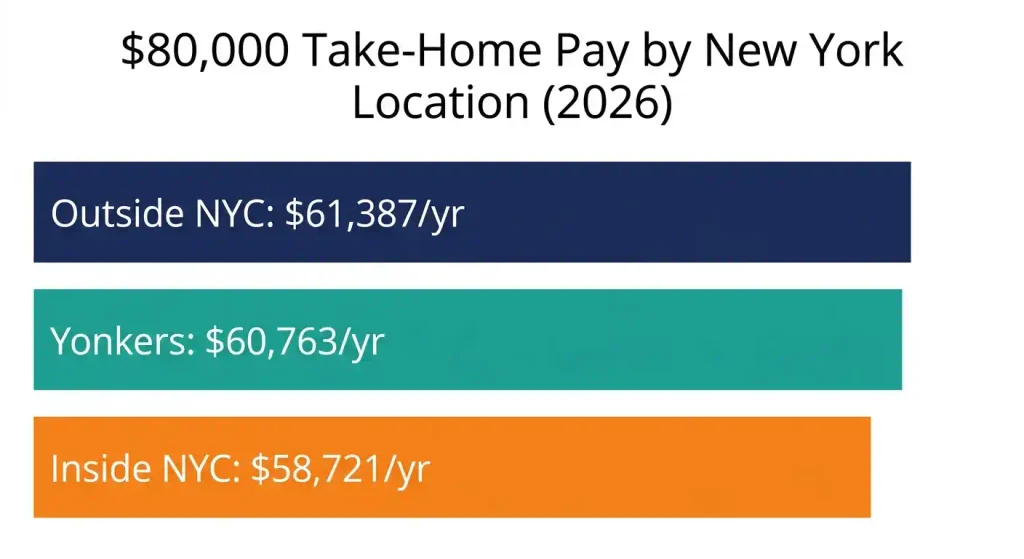
Outside NYC, keep about $61,387. Inside NYC, about $58,721. In Yonkers, about $60,763. The same salary in a no-income-tax state like Florida or Texas would keep even more.
What Does an $80K Salary Actually Mean?
Gross salary minus taxes and deductions equals what lands in your account, taxed in layers, never all at once.
Gross Pay vs Net Pay
Gross pay is your $80,000 salary, about $38.46 an hour or $6,667 a month before anything is withheld. Net pay is what actually deposits after taxes and deductions. The Internal Revenue Service (IRS) and New York State both subtract a standard deduction before touching your income. See the full gross pay vs net pay breakdown for more.
Why $80K Is Not Taxed at One Single Rate
New York and the federal government use progressive systems: early dollars are taxed low, later dollars taxed higher. Your federal marginal tax rate tops out at 22%, but your effective tax rate, the share of $80,000 actually paid in tax, is closer to 23% outside NYC and 27% inside it.
What Comes Out of an $80K Paycheck?
Federal tax, New York State tax, local tax in NYC or Yonkers, and FICA (Social Security and Medicare) at a flat 7.65%. See the full line-by-line breakdown of what taxes come out of a New York paycheck.
$80K Salary Tax Breakdown for 2026
Four layers, federal, state, local where it applies, and FICA, add up to your total tax bill. See our full New York state income tax hub for more.
Federal Income Tax on $80,000
$80,000 is generally your federal adjusted gross income with no other income. Subtract the $16,100 standard deduction for federal taxable income of $63,900, taxed through the 10%, 12%, and 22% brackets for an estimated $8,770 in federal tax.
New York State Income Tax on $80,000
New York subtracts its own $8,000 New York State standard deduction, leaving $72,000 of state taxable income. For 2026, New York’s nine tax brackets, part of New York State personal income tax, run 3.9%, 4.4%, 5.15%, 5.4%, 5.9%, 6.85%, 9.65%, 10.3%, and 10.9%. On $72,000, that produces about $3,723 in tax. The top bracket only applies above $1 million. Your New York adjusted gross income is the starting point before the deduction.
New York City Income Tax on $80,000
The New York City resident tax only applies if you live in NYC. Its four brackets run 3.078% to 3.876%, adding about $2,666 on $72,000 of taxable income. Commuters who live outside the city never pay it.
Yonkers Tax on $80,000
Yonkers residents pay the Yonkers resident income tax surcharge, 16.75% of your New York State tax. On $3,723, that adds about $624, for combined state and local tax of about $4,347.
Social Security and Medicare Taxes
Social Security takes 6.2% ($4,960), Medicare takes 1.45% ($1,160), for $6,120 total FICA. The 2026 Social Security wage base is $184,500, and the 0.9% Medicare additional tax only starts above $200,000.
$80K After Taxes by Paycheck Frequency
Same annual number, split differently depending on how often you’re paid.
Monthly Take-Home Pay
About $5,116 outside NYC, $4,893 inside it. Most New York employers don’t actually pay monthly, so treat this as a budgeting benchmark.
Biweekly Take-Home Pay
About $2,361 outside NYC, $2,259 inside it, across 26 pay periods. Two months a year bring three checks instead of two.
Semi-Monthly Take-Home Pay
About $2,558 outside NYC, $2,447 inside it, across a fixed 24 checks a year.
Weekly Take-Home Pay
About $1,181 outside NYC, $1,129 inside it, across 52 checks.
What Can Lower Your Actual $80K Take-Home Pay?
Pre-tax deductions shrink your tax bill too. Post-tax ones only shrink your check. See the full guide to New York paycheck deductions for how each type works.
Pre-Tax Payroll Deductions
401(k), health insurance, HSA, and FSA contributions all come out before taxes are calculated. Put 5% ($4,000) into a traditional 401(k) and your paycheck drops by only about $2,900, saving roughly $1,100 in tax.
Post-Tax Payroll Deductions
Roth 401(k) contributions and similar deductions come out after tax, lowering your paycheck dollar for dollar with no tax break.
Why an Online Estimate May Not Match Your Paycheck
Filing status, benefits, and residency assumptions vary by calculator. Your pay stub is the final word. The IRS tax withholding estimator gives a more precise federal number.
$80K After Taxes for Different Filing Situations
Filing status changes your deductions and brackets, which changes your take-home.
Single Filer Earning $80,000
About $61,387 outside NYC, $58,721 inside it. Full-year residents report this on New York Form IT-201.
Married Filing Jointly With $80,000 of Household Income
MFJ gets a $32,200 federal standard deduction and $16,050 New York deduction, roughly double the single amounts. On one earner’s $80,000, federal tax drops to about $5,240 and state tax to about $3,121, for take-home near $65,519, noticeably more than the single-filer number.
Head of Household Earning $80,000
HOH requires being unmarried and paying over half the cost of a home for a dependent. The 2026 federal standard deduction is $24,150, and New York’s is $11,200, both between the single and married amounts.
$80K Salary With Dependents
Dependents don’t change the standard deduction directly, but can qualify you for credits like the Child Tax Credit at filing. Claiming them on your W-4 lowers withholding per paycheck.
$80K After Taxes Compared With Other New York Salaries
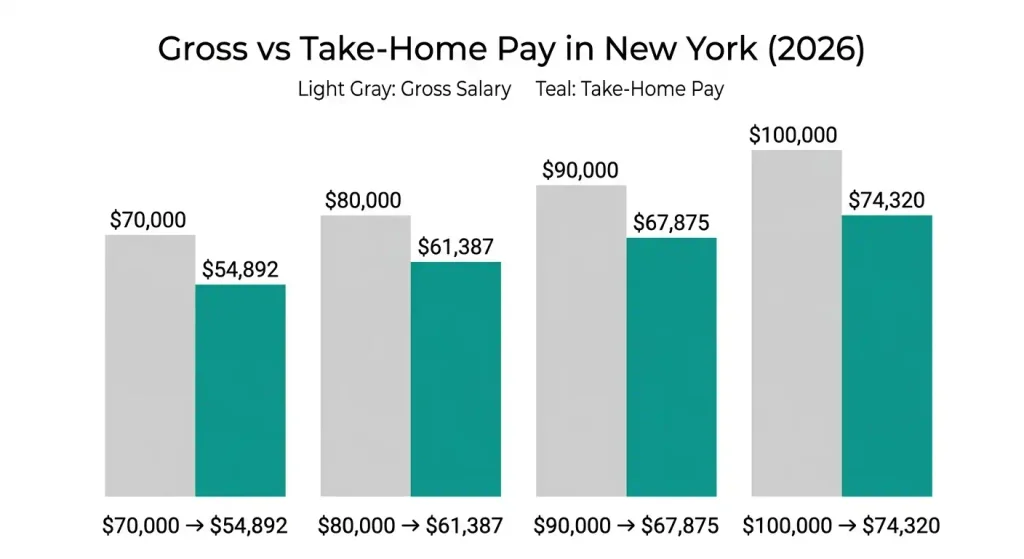
Each $10,000 raise nets roughly 65% in real take-home pay.
| Salary | Est. Take-Home (outside NYC) | vs $80K |
|---|---|---|
| $70,000 | $54,892/yr | -$6,495/yr (-$541/mo) |
| $80,000 | $61,387/yr | — |
| $90,000 | $67,875/yr | +$6,488/yr (+$541/mo) |
| $100,000 | $74,320/yr | +$12,933/yr (+$1,078/mo) |
$70K vs $80K After Taxes
A $10,000 raise nets $6,495 more take-home, since federal, state, and FICA tax also scale up.
$80K vs $90K After Taxes
The pattern holds: another $10,000 nets $6,488 more take-home, not the full $10,000.
$80K vs $100K After Taxes
A $20,000 raise puts about $13,000 in your pocket, not $20,000, since higher brackets take a growing share.
$80K After Taxes in Different New York Locations
Location inside New York moves your number more than almost anything else.
$80K Outside New York City
No local tax applies. Take-home is about $61,387 a year, $5,116 a month.
$80K in New York City
New York City resident tax adds about $2,666. Take-home drops to about $58,721 a year, $4,893 a month, roughly $222 less monthly than the same job pays outside the city.
$80K in Yonkers
The Yonkers resident income tax surcharge lands take-home around $60,763 a year, $5,064 a month, between the no-local-tax and NYC numbers.
Is $80K Enough to Live on in New York?
It’s workable outside NYC, tight inside it.
What $80K Means for a New York City Budget
NYC’s cost of living is among the highest in the country. On about $4,893 a month, rent, a subway pass, and groceries eat most of the check fast, though it’s livable with a roommate.
What $80K Means Outside New York City
On about $5,116 a month, housing stretches further in places like Rochester or Syracuse, leaving more room for savings.
How Much Rent Can You Afford on $80K?
A common guideline caps rent at 30% of disposable income. That’s about $1,468 in NYC or $1,535 outside it.
Real-World $80K New York Paycheck Scenarios
Same salary, four addresses, four different paychecks.
Single Employee Living Outside NYC
Nets about $61,387 a year, roughly $2,361 per biweekly check, no local tax.
Single Employee Living in NYC
Nets about $58,721 a year, roughly $2,259 per biweekly check, about $102 less per check than the same job outside the city.
Employee Living in Yonkers
Nets about $60,763 a year, roughly $2,337 per biweekly check.
Employee Contributing to a 401(k)
A 5% ($4,000) traditional contribution only drops take-home pay by about $2,900, since it also saves roughly $1,100 in tax.
$80K Salary When Your Situation Changes
Moving, working across state lines, or holding two jobs all change your New York tax math.
You Move Into New York During 2026
You owe New York tax only on income earned as a resident, plus any New York-source income earned before the move. This makes you a part-year New York resident. Update your employer with a new address and a New York Form IT-2104.
You Move Out of New York During 2026
The same part-year rule applies in reverse. Update your withholding paperwork as soon as the move happens.
You Work in New York While Living Elsewhere
Nonresidents working in New York generally owe New York tax on New York-source wages, reported on New York Form IT-203. Nonresidents who split work between New York and another state may also need Form IT-2104.1 to allocate wages correctly. Your home state may credit taxes paid to New York. The reverse also holds: New York residents owe tax on all income, even income earned working for an out-of-state employer or while traveling.
You Have More Than One Job
Each employer withholds independently, which can under-withhold once combined. Adjust your W-4 and IT-2104 to account for multiple jobs.
2026 New York Withholding Rules You Should Know
New York State, New York City, and Yonkers each use their own New York tax withholding tables and methods, refreshed for 2026. See our full New York State tax withholding guide for a deeper look.
What Changed for New York State in 2026?
New York revised its personal income tax rate schedules for 2026 under 2025 legislation, effective for any payroll dated January 1, 2026 or later. The New York State Department of Taxation and Finance published the figures in Publication NYS-50-T-NYS, the New York State withholding tax tables and methods, under the New York State Tax Law.
What Changed for Yonkers in 2026?
Yonkers tables were also revised, in Publication NYS-50-T-Y, the Yonkers withholding tax tables and methods, covering both resident and nonresident treatment.
What Should You Know About NYC Withholding?
NYC’s own tables didn’t change for 2026. Employers still use Publication NYS-50-T-NYC, the New York City withholding tax tables and methods.
Form IT-2104 and Your New York Withholding
Form IT-2104 is New York’s version of Form W-4, covering filing status, residency, and withholding allowances. See Form W-4 vs IT-2104 for a side-by-side comparison. Review it after a move, marriage, or new job.
What to Check If Your $80K Paycheck Looks Wrong
Start with gross pay, then check every tax and deduction line. For a walkthrough, see how to read a New York pay stub.
Compare Gross Pay With Your Offer Letter
Confirm gross pay per period matches your annual salary and pay frequency, and that bonus or overtime is included. Your Form W-2 should match at year-end.
Review Every Tax Line
Check federal, New York State, and NYC or Yonkers withholding, plus Social Security and Medicare near 7.65% combined.
Review Benefits and Other Deductions
Compare retirement, health insurance, and HSA or FSA deductions against what you elected.
Check Your W-4 and IT-2104
If numbers still don’t add up, confirm your Form W-4 and IT-2104 reflect your current filing status and allowances. Browse more New York tax forms and withholding guides for specifics.
Common Myths About $80K After-Tax Pay in New York
These four misunderstandings cause most of the paycheck confusion.
Myth: Your Highest Tax Rate Applies to All $80,000
False. Only the last slice of income hits your highest bracket; the rest sits in lower brackets.
Myth: Everyone Earning $80K Pays NYC Income Tax
False. NYC tax only applies to actual NYC residents, not commuters.
Myth: Your Withholding Is Exactly What You Owe
False. Withholding is an estimate; your final tax liability is calculated at filing, which is why refunds and balances due exist.
Myth: Your Take-Home Pay Is Just Salary Minus Income Tax
False. FICA and benefit deductions also come out, on top of income tax.
Frequently Asked Questions About $80K After Taxes in New York
Quick answers to the most common $80K New York questions.
How much is $80K after taxes in New York in 2026?
About $61,387 outside NYC, $58,721 inside NYC.
How much is $80K a month after taxes in New York?
About $5,116 outside NYC, $4,893 inside NYC.
How much is $80K biweekly after taxes in New York?
About $2,361 outside NYC, $2,259 inside NYC.
How much tax do you pay on $80K in New York?
About $18,613 outside NYC, $21,279 inside NYC, combining federal, state, and FICA tax.
Is $80K taxed differently in NYC than elsewhere in New York?
Yes. NYC adds its own resident tax, Yonkers adds a smaller surcharge, and most of New York adds neither.
How much do I take home if I make $80K and contribute to a 401(k)?
A 5% ($4,000) contribution only drops your paycheck by about $2,900, thanks to roughly $1,100 in tax savings.
Why is my $80K paycheck lower than an online calculator says?
Different filing status, benefit deductions, local tax assumptions, or outdated W-4/IT-2104 settings. For more detail, see why your New York paycheck might be lower than expected.
Does an $80K salary mean I take home $80K minus one tax rate?
No. Federal brackets, New York brackets, FICA, and possibly local tax all layer together.
Key Takeaways for an $80K New York Salary
Outside NYC, plan on about $61,387 a year. Inside NYC, plan on about $58,721.
The Numbers to Remember
About $61,387 a year ($5,116 a month) outside NYC, $58,721 a year ($4,893 a month) inside it. The gap is about $2,666 a year, purely from where you live.
The Variables That Matter Most
Filing status, NYC or Yonkers residency, and pre-tax deductions move this number most. Two people earning the same $80,000 can take home noticeably different amounts.
What to Do With Your Estimate
Compare it against your actual first pay stub, budget around the real number, and recheck it if your salary, address, or tax situation changes.
Meet Yasin Ali, Founder
Yasin built NY Paycheck Calculator in 2020 after getting fed up with calculators that treated New York like every other state. Most tools ignore the extra local tax NYC and Yonkers workers pay on top of state tax — or skip New York’s Paid Family Leave deduction entirely.
He keeps the numbers current, checking in regularly against the latest IRS, NY Department of Taxation and Finance, and Paid Family Leave rates.
All results here are estimates based on official sources. For advice specific to your situation, talk to a tax professional.