
New York payroll tax deadlines split into two systems: NYS-45, due four fixed dates each year, and NYS-1, triggered whenever accumulated withholding crosses $700 within a quarter.
After eight years running New York payroll here at NY Paycheck Calculator, I still see employers confuse this NYS-45 and NYS-1 split constantly.
New York allows no extensions, so missing either deadline still triggers real penalties.
New York Payroll Tax Deadlines at a Glance
This section breaks down which 2026 date applies to your NYS-45 filing and when NYS-1 kicks in for your specific payroll.
2026 New York Payroll Tax Deadline Calendar
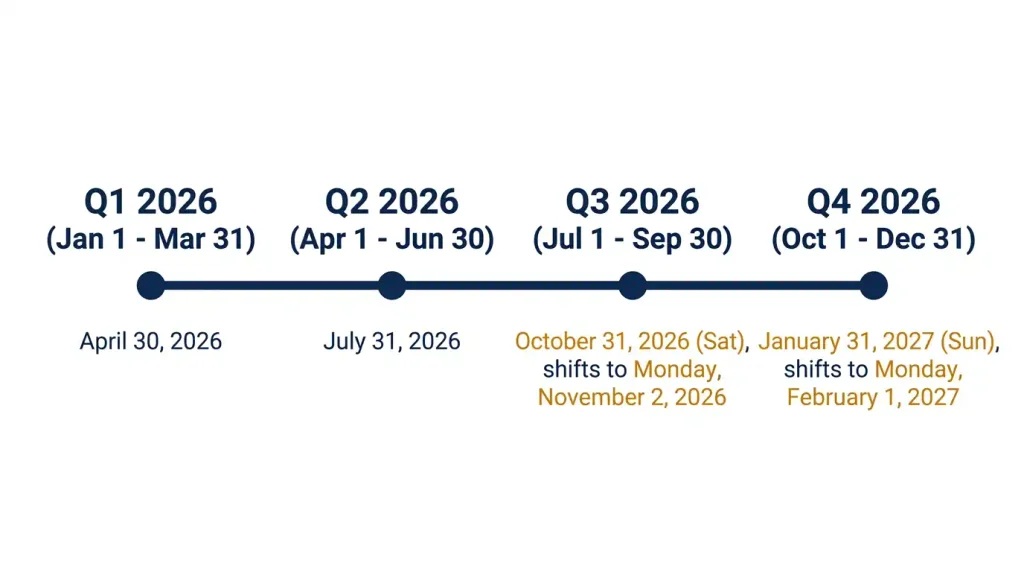
NYS-45 is due April 30, July 31, and October 31, 2026, and January 31, 2027 for Q4, which falls on a Sunday and shifts to February 1, 2027. NYS-1 has no fixed date. It triggers once accumulated withholding crosses $700. New York grants no extensions on this 2026 New York tax calendar.
| Quarter | Period Covered | NYS-45 Due Date |
|---|---|---|
| Q1 2026 | Jan 1 – Mar 31 | April 30, 2026 |
| Q2 2026 | Apr 1 – Jun 30 | July 31, 2026 |
| Q3 2026 | Jul 1 – Sep 30 | October 31, 2026 (Sat), shifts to Monday, November 2, 2026 |
| Q4 2026 | Oct 1 – Dec 31 | January 31, 2027 (Sun), shifts to Monday, February 1, 2027 |
Which New York Payroll Tax Deadline Applies to You?
Every withholding employer owes NYS-45 each quarter. NYS-1 applies only once withholding hits $700 in a quarter. Below $700, wait and report on NYS-45.
The Key 2026 Dates Employers Should Put on Their Calendar
Remember April 30, July 31, October 31, and January 31 for NYS-45. NYS-1 has no matching dates since it follows your payroll, not the month. The Internal Revenue Service runs Form 941 on its own separate schedule.
Four fixed NYS-45 dates, one moving NYS-1 rule. Mixing them up is the top mistake.
How New York Payroll Tax Deadlines Work
New York payroll tax covers state, city, and Yonkers withholding plus unemployment insurance for anyone classified as an employee rather than an independent contractor. NYS-1 pays. NYS-45 reports.
What Taxes and Payroll Obligations Are Covered
You withhold New York State income tax withholding, called New York State withholding tax, using Form IT-2104. New York City withholding tax or Yonkers withholding tax applies based on residence. Unemployment insurance is an employer-only cost, never taken from wages.
Why New York Uses Both NYS-1 and NYS-45
NYS-1 moves cash fast once withholding hits $700. NYS-45 reconciles the full quarter: wages, withholding, and unemployment insurance. Paying through NYS-1 does not remove the NYS-45 requirement.
What Determines Your Payroll Tax Filing Frequency
Employers who withheld over $15,000 the prior year are 3-day filers. Everyone else, including new employers, starts as a 5-day filer. PrompTax employers follow a separate monthly schedule, not the $700 rule.
Two forms split the work: NYS-1 moves cash fast, NYS-45 closes the quarter.
2026 NYS-45 Quarterly Deadlines
NYS-45 has four quarterly deadlines in 2026, each covering three months of wages, withholding, and unemployment insurance.
First Quarter: January 1 Through March 31
Due April 30, 2026. Report wages, withholding, and unemployment insurance for January through March.
Second Quarter: April 1 Through June 30
Due July 31, 2026. Include only payrolls with a pay date in this window.
Third Quarter: July 1 Through September 30
Due October 31, 2026, a Saturday, so the deadline moves to the next business day, Monday, November 2, 2026. File by Friday, October 30 to stay safe.
Fourth Quarter: October 1 Through December 31
Due January 31, 2027, a Sunday, so the real deadline is Monday, February 1, 2027. This quarter is also your last chance to true up year-end payroll for 2026.
Four quarters, four hard NYS-45 deadlines. The Q4 one always lands in a new year.
2026 New York Payroll Tax Forms You Need to Know
New York uses four main documents: NYS-1, NYS-45, NYS-50, and the 2026 withholding tables, all covered in our New York tax forms and withholding guides.
Form NYS-1
NYS-1 is the Return of Tax Withheld. It triggers at $700 accumulated withholding. Due 3 or 5 business days after that payroll, per your filer status. Full instructions are in Publication NYS-1-I.
Form NYS-45
NYS-45 is the Quarterly Combined Withholding, Wage Reporting, and Unemployment Insurance Return. It reports withholding, employee wages, and unemployment insurance together, every required quarter.
Form NYS-50
NYS-50 is the Employer’s Guide to Unemployment Insurance, Wage Reporting, and Withholding Tax, officially Publication NYS-50. It is a rulebook, not a return.
2026 NYS Withholding Tables
NYS-50-T-NYS and NYS-50-T-Y were revised for 2026 with a 0.10 percentage point cut to the bottom five 2026 New York tax brackets. NYS-50-T-NYC covers New York City residents and was unchanged, since no legislative rate change applied there. See our calculation methodology for how these tables translate into an actual paycheck. If an employee asks why their check changed, point them to why your New York paycheck may look lower.
NYS-1 pays, NYS-45 reports, NYS-50 is the instruction manual.
New York Payroll Tax Deadlines vs. Federal Payroll Deadlines
New York and the federal government run separate deadlines. Filing one never satisfies the other.
New York State vs. IRS Payroll Deadlines
New York uses NYS-45 and NYS-1. The Internal Revenue Service uses Form 941 for withholding and FICA taxes covering Social Security and Medicare. Q1 2026 Form 941 is due April 30, Q2 is due July 31, and Q3 shifts to November 2 since October 31 is a Saturday. Form 940 reports FUTA tax and normally is due January 31, and Form W-2 and Form W-3 go out the same window, but since January 31, 2026 is a Saturday, all three shift to February 2, 2026. IRS Publication 15, known as Circular E, and IRS Publication 509 cover the full federal schedule.
New York State vs. NYC and Yonkers Withholding
State withholding applies to every New York employee. New York City withholding tax and Yonkers withholding tax apply only to residents. All of it reports through NYS-45.
Payroll Tax Payment vs. Payroll Tax Return
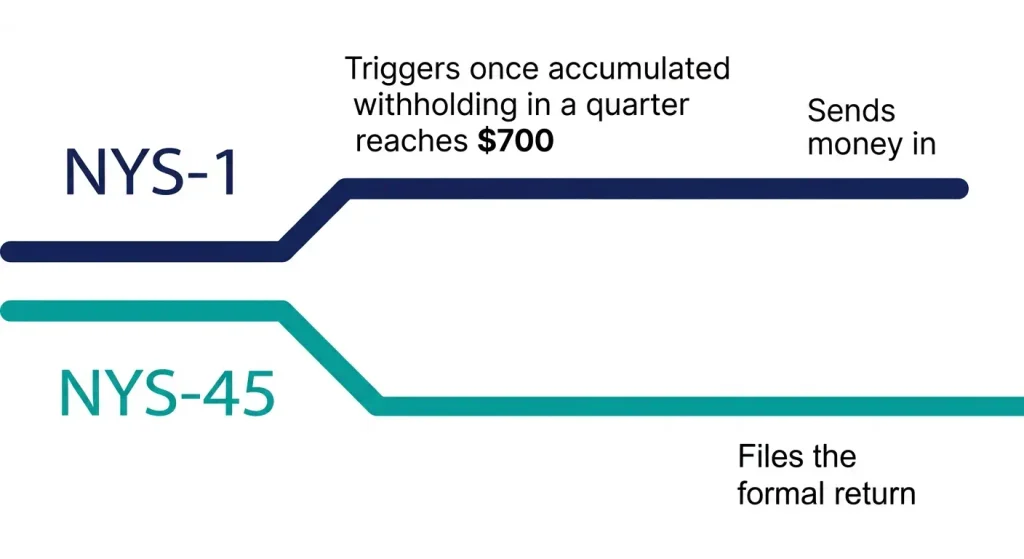
NYS-1 sends money in. NYS-45 files the formal return. Treating them as one deadline leaves a paid balance with a missing return, which still triggers a penalty.
Federal, state, and city payroll taxes run separate calendars. Paying one never checks the box for another.
What You Must File and Pay With NYS-45
NYS-45 reports employee-level wages and withholding plus unemployment insurance, every required quarter, mirroring how New York paycheck deductions show up on each employee’s check.
Quarterly Wage and Withholding Information
Report wages and withholding for every employee paid that quarter, the same categories covered in what taxes come out of a New York paycheck. Totals must match what you paid through NYS-1, the same gross pay vs net pay figures your employees see on payday.
New York Unemployment Insurance Reporting
Unemployment insurance is an employer cost reported on the same NYS-45, which is why New York calls it a combined return.
Zero-Wage and Zero-Withholding Quarters
Zero payroll still generally requires a filed NYS-45. Seasonal employers file even in off-season quarters. Only formally ceased operations are exempt.
NYS-45 is still required in a quiet quarter. It ties wages, withholding, and UI together.
NYS-1 Deadlines: The $700 Rule Explained
NYS-1 triggers once accumulated withholding in a quarter reaches $700.
| Filer Type | Prior-Year Withholding | NYS-1 Deadline |
|---|---|---|
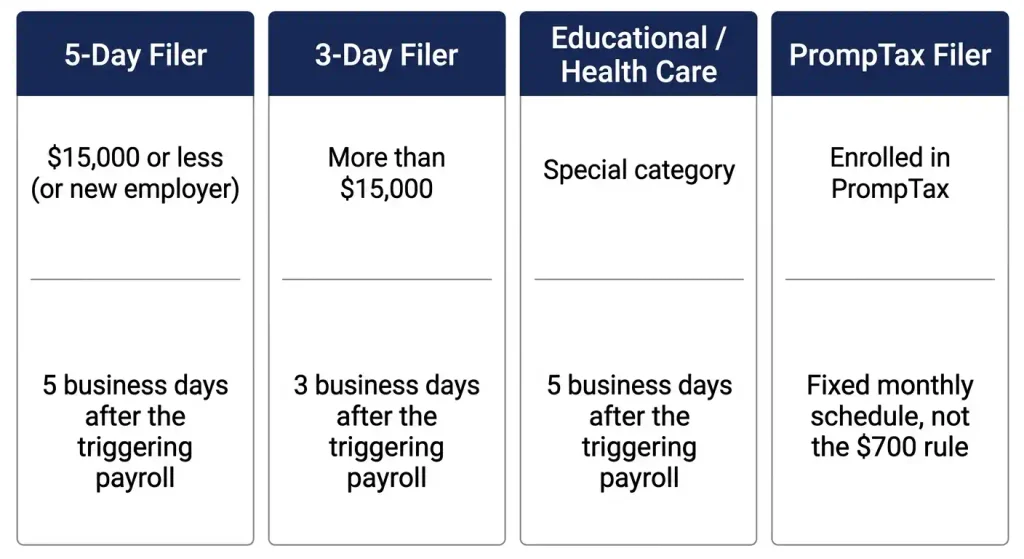
| 5-Day Filer | $15,000 or less (or new employer) | 5 business days after the triggering payroll |
| 3-Day Filer | More than $15,000 | 3 business days after the triggering payroll |
| Educational / Health Care | Special category | 5 business days after the triggering payroll |
| PrompTax Filer | Enrolled in PrompTax | Fixed monthly schedule, not the $700 rule |
When You Must File NYS-1
The payroll that crosses $700 triggers NYS-1. This resets every quarter. Waiting until NYS-45 to remit after crossing $700 carries the same late-payment risk as skipping NYS-1.
5-Day Filers
Employers who withheld $15,000 or less last year get 5 business days after the triggering payroll. New employers start here too.
3-Day Filers
Employers who withheld more than $15,000 last year get 3 business days. The Tax Department can notify you of a different schedule.
Educational Organizations and Health Care Providers
These get 5-day treatment under the New York Tax Law, even above the 3-day threshold.
PrompTax Filers
PrompTax employers pay on a fixed monthly schedule, not the $700 rule.
$700 is the trigger. 3 or 5 business days depends on last year’s withholding.
How to Calculate Your NYS-1 Due Date After Payroll
Count 3 or 5 business days from the payroll that crosses $700.
Start With the Payroll That Crosses $700
Add this payroll’s withholding to your accumulated total. If it hits $700, this payroll is your trigger.
Count 3 or 5 Business Days Correctly
Start counting the next business day. Skip weekends and legal holidays. Apply 3 or 5 days per your filer status.
Multiple Payrolls in One Week
New York’s payroll week runs Sunday through Saturday. With more than one payroll in a week, NYS-1 waits until after the last one.
Biweekly Payroll Example
A March 6 payroll withholds $500. A March 20 payroll adds $400, hitting $900. March 20 is the trigger. Anything left still reports on Q1 NYS-45.
Weekly Payroll Example
A Friday, June 5 payroll crosses $700, the only payroll that week. June 5 is the trigger, and the countdown starts the next business day.
The trigger is the payroll that crosses $700. Counting starts the next business day.
Real-World New York Payroll Deadline Scenarios
Six real situations show how the $700 rule plays out.
Scenario 1: Withholding Stays Below $700
A shop withholds $150 per payroll across four payrolls, totaling $600. No NYS-1 triggers. The $600 reports on NYS-45.
Scenario 2: Payroll Pushes Withholding Over $700
A restaurant at $550 runs a payroll withholding $300 more, hitting $850. As a 5-day filer, NYS-1 is due five business days after that payroll.
Scenario 3: Three Payrolls Occur in One Week
A staffing company runs Monday, Wednesday, and Friday payrolls. Withholding crosses $700 on Wednesday. NYS-1 is not due until after Friday’s payroll.
Scenario 4: Quarter Ends Between Payrolls
A pay week runs March 26 through April 1, crossing the quarter line. If withholding hits $700 in that week, NYS-1 applies at the last payroll, and NYS-45 reconciles the correct quarter.
Scenario 5: Employer Has NYC or Yonkers Employees
Manhattan residents get New York City withholding tax. Long Island residents do not. Both report on the same NYS-45.
Scenario 6: New Employer Runs Its First Payroll
A new bakery’s first payroll in February 2026 starts as a 5-day filer by default, since there is no prior-year record yet.
Every scenario comes down to two questions: did this payroll cross $700, and did more than one payroll land in the same week?
What Happens When the Quarter Ends?
Quarter-end timing gets special NYS-1 handling but never removes the NYS-45 requirement.
Quarter Ends Between Payrolls
If a pay week straddles quarter-end and hits $700, NYS-1 still waits until the last payroll of that week.
Less Than $700 Remains After the Last NYS-1
A leftover balance under $700 after your last NYS-1 does not need its own filing. It reports on NYS-45.
Why NYS-45 Is Still Required After NYS-1 Payments
NYS-1 payments never replace NYS-45’s wage report, withholding reconciliation, and unemployment insurance total.
Quarter-end gets special NYS-1 handling, but NYS-45 is still required.
How to File New York Payroll Taxes in 2026
Nearly all New York payroll filing happens electronically through Online Services.
NYS-1 Web File
File NYS-1 through New York Business Online Services using the New York Web File system, paying by ACH debit.
NYS-45 Web File
NYS-45 files the same way each quarter, with withholding and unemployment insurance paid together.
Other Electronic Filing Methods
Payroll services often use Web Upload. FSET, short for Federal/State Employment Taxes, is another accepted method. PrompTax employers use their own system.
Electronic Filing Requirement
Electronic filing is required in nearly every case. Paper filing only applies under narrow exceptions.
Nearly every 2026 filing happens online. Paper is the exception.
How to Correct a New York Payroll Tax Filing
Amend NYS-1 or NYS-45 as soon as you find an error.
When to Amend NYS-1
Amend NYS-1 for a wrong payroll date or additional tax due before NYS-45 is filed.
When to Amend NYS-45
Amend NYS-45 for wrong tax amounts, wage errors, a ceased-wages date, or a business sale, reported for the correct quarter.
Correcting an Overpayment
An overpayment can apply as a same-quarter credit, or a later credit or refund through NYS-45. Keep your records.
Fix mistakes fast and fully, before they grow into penalties.
What Happens If You Miss a New York Payroll Tax Deadline?
Missing a deadline risks penalties, interest, and a higher unemployment insurance rate.
Late Filing Penalties and Interest
Late filing and late payment are separate violations, both carrying penalties and interest.
Incorrect Withholding or Underpayment
Wrong withholding can often be corrected on your next filing. Larger errors may need an amended NYS-1.
Late Unemployment Insurance Payment
Late unemployment insurance contributions get factored into your experience rating, which New York recalculates annually, and can raise your future UI rate or affect federal credits.
One missed deadline can trigger late filing, late payment, and a higher UI rate.
Common New York Payroll Tax Deadline Mistakes and Myths
Most New York payroll mistakes come from mixing up NYS-1, NYS-45, and federal deadlines.
Myth: Every New York Payroll Tax Is Due Quarterly
NYS-45 is quarterly. NYS-1 triggers at $700, any time in the quarter.
Myth: NYS-1 Replaces NYS-45
NYS-1 payments never replace NYS-45’s wage and unemployment insurance reporting.
Myth: $700 Means You Have Exactly 3 Business Days
3 or 5 days depends on last year’s withholding, not the $700 trigger itself.
Myth: A Payroll Service Means the Employer Has No Responsibility
The employer stays responsible even with a payroll service. Check confirmations and keep your own records.
Myth: No Employees Paid Means No NYS-45
Zero payroll usually still requires NYS-45, aside from narrow ceased-operation exceptions.
Myth: Federal Payroll Deadlines and New York Deadlines Match
Federal Form 941 timing has no effect on New York’s NYS-45 or NYS-1 deadlines.
Almost every mistake comes from assuming one form or government covers what only the other does.
New York Payroll Tax Deadline Checklist for Employers
Run this four-step check every payroll cycle, and keep how to read a New York pay stub handy for cross-checking wage totals.
Before Each Payroll
- Confirm employee withholding information
- Check your accumulated New York withholding total
- Confirm your filer status
- Watch the $700 threshold
After a Payroll Crosses $700
- Confirm NYS-1 is triggered
- Confirm your filer status (3-day or 5-day)
- Calculate the exact due date
- Schedule and confirm payment
At the End of Each Quarter
- Confirm the NYS-45 due date
- Reconcile totals against NYS-1 payments
- Review unemployment insurance figures
- Confirm electronic filing and payment
Before Submitting Any Return
- Verify employer account information
- Verify payroll dates and wage totals
- Verify withholding amounts
- Save your confirmation
A simple four-step checklist catches nearly every New York deadline problem.
Official New York Payroll Tax Resources for 2026
The New York State Department of Taxation and Finance and New York State Department of Labor are the official sources. For your own take-home numbers, try our New York paycheck calculator, and for more employer-side guides, browse our New York payroll employer compliance hub.
New York State Tax Department Resources
The New York State Department of Taxation and Finance publishes official withholding tax due dates, NYS-1 and NYS-45 forms, filing resources, and penalty information.
New York Department of Labor Resources
The New York State Department of Labor covers unemployment insurance contribution rates, wage reporting, and employer registration.
2026 Forms and Publications
Keep NYS-45-I, NYS-50, NYS-50-T-NYS, NYS-50-T-NYC, and NYS-50-T-Y on hand for 2026.
Every rule here traces back to official New York State publications.
Frequently Asked Questions About New York Payroll Tax Deadlines
When are New York payroll taxes due in 2026?
NYS-45 is due April 30, July 31, October 31, and January 31, 2027, shifting to February 1, 2027 since that date is a Sunday. NYS-1 triggers 3 or 5 business days after crossing $700.
When is NYS-45 due for the first quarter of 2026?
April 30, 2026, covering January through March wages, withholding, and unemployment insurance.
When do I have to file NYS-1?
Once accumulated withholding hits $700 in a quarter, filed 3 or 5 business days after that payroll.
What happens if I withhold less than $700 in a quarter?
No NYS-1 is required. Report and remit the full amount on NYS-45. Example: $600 withheld all quarter needs only NYS-45.
Do I still file NYS-45 if I already filed NYS-1?
Yes. NYS-45 still needs the full wage report, withholding reconciliation, and unemployment insurance figures.
What if my New York payroll tax deadline falls on a weekend?
Fixed NYS-45 dates move to the next business day. NYS-1 counts business days only.
What happens if I miss a New York payroll tax deadline?
You risk penalties and interest for late filing, late payment, or both. Fix it immediately.
Are New York payroll taxes filed separately from federal payroll taxes?
Yes. New York uses NYS-45 and NYS-1. The Internal Revenue Service uses Form 941 and its own deposit system.
Does New York require electronic payroll tax filing?
Yes, for nearly every employer, through New York Business Online Services.
Meet Yasin Ali, Founder
Yasin built NY Paycheck Calculator in 2020 after getting fed up with calculators that treated New York like every other state. Most tools ignore the extra local tax NYC and Yonkers workers pay on top of state tax — or skip New York’s Paid Family Leave deduction entirely.
He keeps the numbers current, checking in regularly against the latest IRS, NY Department of Taxation and Finance, and Paid Family Leave rates.
All results here are estimates based on official sources. For advice specific to your situation, talk to a tax professional.